Die Eigenheit has just been paid a visit by Matthew Chan, who informed me that the John Burley discussion groups at the MasterMind Forums have been moved here.
Although this has, for the time being, broken all of my links to the individual posts there, at least everything hasn't been thrown down the memory hole. I should get around to the annoying task of fixing the links sooner or later.
Mr. Chan would like it to be known that he doesn't consider himself a "guru" or a "Burleyist", though I can't recall ever applying either of those labels to him.
Showing posts with label John Burley. Show all posts
Showing posts with label John Burley. Show all posts
Thursday, April 05, 2007
Matthew Chan No Longer Hosting Burley Forums

Saturday, September 09, 2006
Former Burleyist – Joe Arlt
On September 3rd this blog received a visit from an anonymous commenter who claimed to be Joe Arlt. Arlt is the author of the tape set Wrap Your Way to Wealth, and he was once, arguably, the world’s premier Burleyist. Based on both the content of the comment and the location of the commenter, I have little reason to doubt that this was the actual Joe Arlt.
Here is what he had to say:I was recently directed to your site and its comments and felt compelled to respond. Youu state that you found zero (your italics) evidence that I own any investment properties. Just how hard did you look? For obvious reasons explained in my tape set, the great majority of my holdings are not in my personal name. However, a quick recent search of the tax records for the cities in my area revealed no less than 7 properties with my name as legal title holder. There would likely have been a few more as of your February 2006 comments, as we have sold quite a few properties since then. This is a small fraction of what I own, and I’ll be taking steps to correct the public record for even those. You could have also reviewed recent MLS listings, which would have revealed many with me as listing agent and the required disclosure “Owner/Agent”. But if this issue was of such great importance to you, why did you not just contact me directly? We’re easy to find. My company is in the phone book, the local BBB, etc. This would probably a better approach than just libeling me, to everyone with access to the web, wouldn’t you say?
Thanks, Joe, for taking the time to share your thoughts. I honestly appreciate it.
For the record, I have never stated that I had over 400 properties in Virginia. At our peak we had an interest in probably 250 in that state, with the rest in several others. Due to lease option cash outs (yes, they do happen), sales, and partnership unwindings, we’re now down to around 250 total. We will likely be closer to 200 by year end, due to further cash outs, profit taking, etc.
As far as my tape set is concerned, you are certainly entitled to your opinion. The program has been off the market for several years and was never meant to be a major profit center, as I am not a professional speaker. So I have no financial interest in what you may care to publish regarding it. However, I will say that everything pertinent I knew about this business at that time made its way onto those tapes and the included CD-ROM. There may not have been detail for you, but know that there was enough for me and many others to build significant portfolios. Using just one of my methods to buy just a couple of houses a month (a very part-time effort) from 2000 (a date you mention) to now, a period of low interest rates and high appreciation (in many areas), could have been very profitable for anyone willing to make the effort. But if you don’t make the effort, or need to have every answer before you start, no program will work for you.
And regarding your innuendo concerning my discontinued association with John Burley’s discussion forum and web site, I am stunned by how badly you have missed the boat on this issue, given your obvious obsession with this man and his activities. The slightest bit of research would have revealed that we were at one time partners in a business that acquired many houses and that our association ended when the partnership ended. I’m afraid that is the extent of this “mystery.”
In summary, “investigative journalism” becomes “yellow journalism” very quickly when the journalist chooses to avoid learning facts that do not support his case. If you’ve decided that bashing people you know little about is the best use of your time, then I’d suggest spending some of that time gathering all the facts first. You will be taken a lot more seriously as a result.
Joe Arlt September 3, 2006
In response to the questions in your first paragraph, I confess to not looking all that hard. I am nowhere near as adept at navigating Virginia’s public records as I am Arizona’s, and frankly you were not my primary focus. As such, the matter was not of any “great importance” to me. Note that I was specifically calling into question your claim about 400 properties, which you seem to be confusing with whether or not you’re easy to find in the phone book. The burden of proof is on you, not me, to demonstrate the truth of your extraordinary claim. If you care to provide me with any specific evidence then I will be happy to update my blog post to reflect the new information.
By the way, please point out where I libeled you, because I can’t find it.
Tuesday, August 08, 2006
John Burley's Latest Antics
Let’s pretend, for a moment, that you own a rental property, free-and-clear.
For argument’s sake, and to help complete the picture in your mind’s eye, lets say it’s in Phoenix, AZ, and its address is 3844 W Caribbean Lane.
Further, let’s say it’s worth around $220,000, and you can rent it for $1,500 per month. So, your gross yearly receipts on this $220,000 asset are $18,000.
As an investor, you know you need to constantly be asking yourself whether or not your money is performing for you as well as it could be. In the above situation, you have to wonder if that $18K/year is the best you could get on the $220,000 invested in the house. It’s actually very easy to imagine a realistic situation where borrowing against this equity can make you better off (in other words, using the tool of “leverage” to your advantage).
Let’s say you looked around town and found two other properties for which you could get $1,600 per month in rent. Imagine, for the sake of argument, that you offered $222,750 each for those houses, and the sellers accepted your offer.
You take out a 30-year loan for $148,500 against your rental property, at 7.25% interest. This gives you a monthly loan payment of $1013, leaving you still clearing $487/month in gross rents on your original property.
If you split that $148,500 in two and put down $74,250 on each of the new places, you can then take out two more loans of $148,500 each, at 7.25% interest. You’ll be clearing $587 per month on each of the new houses.
Notice what happened here: Your total equity is still $220,000, but now your gross yearly receipts are $19,932, instead of $18,000. Pretty cool, huh?
Why am I telling you all this?
Well, it turns out that my favorite guru, John R Burley, recently took out a loan against one of the first houses he ever bought in Phoenix. I’m not sure what he did with the money, but I wouldn’t be surprised if it was for something along the lines of the above hypothetical.
Still, it’s an interesting question, isn’t it? In the public figure of John Burley we have a guy who - when he's not claiming that no bank will lend to him, that is - goes on and on about how you should use “money partners,” how you should hide behind complicated corporate structures, how you should avoid owning rentals, and how you should live debt free… and yet here he is transparently borrowing a huge chunk of money on a property that I’m pretty sure is a rental. What gives?
I know that if I were actually a student of Burley’s I would really like to learn the answer to that question. And if Burley were truly interested in educating his students then I can’t imagine that he’d have a problem answering it, either. Isn’t it a perfect educational opportunity? I’m sure his answer would be instructive, and the above scenario is how I imagined he might answer it.
So, here I give you a tool you can use yourself to determine whether or not Burley’s claims to honesty, integrity, and a genuine interest in educating people in “the money game” are true. I encourage you to do the following:
- Go to the Mastermind Forum.
- Create a username & password.
- Post a message something like the following:
Dear Mr. Burley, I noticed that you recently borrowed $148K against one of the first houses you purchased in Phoenix—one that doesn’t appear to have been one of your “wraps.”Then, see if your message lasts longer than 6 hours on the site. Given that your post is not likely to survive more than a few hours, you have to wonder. Just what is it that Burley is afraid of? Why the unwillingness to be up front about this? Is all perhaps not well in Burley Land? What is he hiding?
See this link here for the loan document in question: http://recorder.maricopa.gov/recdocdata/GetRecDataDetail.asp?rec=06-0988815&bid=&sar=UnOfficial&bdt=6/1/2006&edt=8/7/2006
Didn't you say that no bank will lend to you because you own too much real estate? Anyway, I was wondering if you might share with us what you planned to do with the borrowed funds, which are presumably to be used in the purchase of more investments.
I realize this may be none of my business, but I thought that since you always advocate using money partners and living debt free then it would be educational for us neophyte investors to learn of an investment situation that doesn’t call for that.
Good Investing,
[your name]
Sunday, July 02, 2006
Index to My John Burley Posts
Well, I’ve finally said all that needs to be said about John Burley (I hope)! 23 posts in all—over a third of this entire blog. Somewhat ironically, most people who find Die Eigenheit via the search engines do it with some variation of the key words john burley progressive profits scam, which takes them to my shortest Burley post, which is a post that directs them to other skeptical sites! Bummer.
Anyway, since I’ve written so many posts critical of John Burley and his real estate investment “advice” over the past several months, I figured it would be a good idea to create a single post that links to all of them, with short descriptions of the contents of each. I guess that’s not an index, really. More like a table of contents, I suppose. I’ve listed them in a suggested reading order, but feel free to skip around.
I recommend you start with A Brief Introduction, which goes into why I decided to write all these criticisms of John Burley and gives the barest sketch of what exactly a “wrap” is.
Next, check out my post that asks, “Is John Burley a ‘guru,’ or a fraud?” I take a detailed look at the claims John Burley makes on The Secrets of Professional Investors Made Easy, a tape set of Kiyosaki’s 1997 seminar in Australia which featured John Burley. Of course it’s impossible to say that Burley is running a scam without creating an exposure to charges of libel, so I leave it to you, the reader, to answer the question in the post’s title yourself.
I recommend you then check out my post on John Burley’s 7 Levels of Investor. I notice that Burley has very recently updated his web site (and in the process broken all of my links to his pages!), to better highlight what has basically become his “brand.” It’s smart to stick with what works, no doubt. Interestingly, he’s allowing people to review his products directly on his site. That could be fun! Will he be able to handle the negative reviews?
You might then be interested in reading my review of John Burley’s book, Money Secrets of the Rich. I highlight some pretty incredible claims that he makes.
As you probably know, John Burley has a “Boot Camp.” Is it really worth $5000? I doubt it. In my post on John Burley’s Dog and Pony Show I give one reason why.
Burley used to publish a quarterly newsletter (maybe he still does. I’m not sure). I compare the advice he gives in one of them with the advice that you’ll get out of your newspaper’s horoscope. See if you can tell the difference.
Burley’s biggest claim to fame is, arguably, the “hundreds” of houses that he owns. I took a look at the public record in an attempt to figure out the real number. It’s actually higher than I thought it was going to be. You can read more detail in the post on Burley’s Investment Properties and Investor Partners.
Given all those houses, Burley has to have some way of finding home sellers and then attracting homebuyers. One way, it seems, is with an eBay Store. Another way is with a website. I should point out that I have been watching ez2own1.com for several months, now, and I haven’t once seen an old property come down or a new property go up. I am therefore convinced that ez2own1.com is a dummy site (though the properties listed are, in fact, Burley houses). Now that Burley seems intent on revamping his web pages, however, we may soon see this changed. I will update this post as needed.
Burley sells houses to people with bad credit. Not surprisingly, this leads to a lot of foreclosures.
Burley loves to crow about his high returns on investment. I tackle his claims based on economic theory in this post, and then follow that up with a more concrete analysis in this post. Then I top it all off with this one, where I look at what Burley had to give up to become a "guru."
As I mentioned above, there are other skeptical sites out there on the web, but not many. I highlight a couple of them.
In my transactions and legal entities posts I present some raw data I pulled from the public record, mostly in preparation for my more detailed posts later on.
Burley has many “students.” He claims that his students’ success rate is the best in the business. I liken the behavior of some of these people to what you might see in a religious cult, which is why I decided to call them “Burleyists.” I’ve written a number of posts highlighting a particular person and what makes them interesting. You can find them here:
Mike Hay
Chris Bridgeman
ChavaRica
Robyn Grinter
Robert Yang
A Burleyist?
Troy Mann
Joe Arlt
That’s it! I don’t foresee writing any more John Burley posts, but you never know. If I do, though, I’ll be sure to put a link to it here.
Update: John Burley's Latest Antics - I wonder why Burley borrowed such a huge chunk of money and won't talk about it.
Saturday, July 01, 2006
John Burley's Opportunity Cost
In my previous John Burley post, I touched briefly on the value of Burley’s time. I’d like to revisit this topic here, exploring its implications in more detail.
Recall that John Burley moved from Northern California to Phoenix in late 1990, leaving behind, apparently, a lucrative financial planning business, in which Burley claims he was grossing $140K per year. Recall also that Burley says the typical spread for his wraps is between $200 and $400 per month, which he splits, along with the buyer’s deposit, 50-50 with his investors. For the sake of argument, lets assume Burley’s average monthly net for his houses is $150. From this it’s a simple matter to figure out that, not counting the buyer’s deposit money, Burley needs to own/manage (hereinafter I’ll just say “own”) at least 78 houses to match the yearly income he has given up.
Of course the number 78 makes the obviously dubious assumption that the homes are never vacant, and that Burley has zero business expenses. Say he leases a small office for $500/month, pays an additional $200/month in utilities, and hires a salaried office assistant for $18,000/year. That brings us to 93 houses. Add in a modest 4% vacancy rate, and we’re up to 97.
Burley claimed in 1997 that he owned 133 homes. I personally think it was probably somewhere between 90 and 100, but it’s difficult to be definitive, and combing the public record is tedious, so I’m willing to tentatively take him at his word. Nonetheless, Burley didn’t suddenly own 133 income-producing properties on January 1st, 1991. He had to build up a portfolio over time. Below is a count of homes I could confirm he owned by the end of each year listed:
1990 – 5 (monthly income: $750)
1991 – 13 (monthly income: $1950)
1992 – 23 (monthly income: $3450)
1993 – 25 (monthly income: $3750)
1994 – 47 (monthly income: $7050)
1995 – 57 (monthly income: $8550)
If we assume that I’ve missed, say, 20 properties along the way, that brings us to 77 houses—just under the bare minimum needed to bring Burley back to his 1990 financial planner’s income (I shouldn’t have to point out again that I’m assuming no business expenses, here).
Is it any wonder, then, that Burley sought, in the meantime, to build a cult of personality and become the “real estate guru” that he is today, thereby supplementing what can only be construed as a meager business income with a comparatively more lucrative take selling $5,000 seats at seminars, $100 “wealth manuals,” and $300 tape sets?
John Burley's ROI Redux
John Burley makes a point to frequently tout the “Level 5 Active Investor” rates of return he and his successful students get on their “investments”—and how you can do it, too, once you’ve learned the “secrets.” I’m sure Burley, being the consummate slick sales guy, recognizes that, along with the promise of “financial freedom,” his claim that his “cash flow” technique consistently provides “20-100%+ returns” is his most alluring siren song.
I have grappled with Burley’s return on investment (ROI) claims from a more theoretical perspective in prior posts. I’m fairly confident that my analyses were persuasive and comprehensive. However, Burleyists could still use my focus on the abstract to their rhetorical advantage, saying, “Psychobabble! Einzige’s theories are all well and good, but the real-world success of John Burley and his students clearly refutes them.” If you go by what Burley and his students tell you then, yes, they might have a point. But you’re not going to get the whole story by going through Burley’s promotional materials, reading the mastermind forums, watching the videos from Progressive Profits, or, I suspect, even attending Burley’s expensive weeklong Boot Camp. Something tells me that Burley isn’t likely to be making his tax records available any time soon, either. What we’re left to work with, then, isn’t much more than theory and conjecture.
On the other hand, there is one thing we do have: the public record. We can use that, plus some theory and educated guessing, I believe, to shed more light on an area that Burley would undoubtedly prefer stayed shrouded in darkness.
Burley himself provides us with an excellent starting point on pages 379 to 388 of his book, where, in the process of going over his “cash flow strategy,” he gives concrete examples of actual properties his company has managed over the years. Burley stresses to his readers that the homes he highlights were “not special deals… I selected these for illustration because they are very typical…” Fortunately for us, he gives just enough information about each property to make the relevant documents easy to find in the online database of the Maricopa County Recorders Office.
Here is one of his examples:
3320 W San MiguelFollow the links to the recorded documents I’ve provided in the above quote and you’ll find that the public record bears out Burley’s dates and dollar figures. However, in detailing this example, Burley has engaged in significant distortions and withheld pertinent information. In no particular order, these include:
I acquired this property in May 1998. It is a typical ‘Lunch Pail Joe’ house. Built in 1958, it is a 110 square meter, 3-bedroom, 2-bathroom house. It had a swimming pool which required replastering (responsibility of the new buyer). The inside and exterior had just been painted by the lender.
It was a lender foreclosed property. The purchase price was $58,513 with monthly payments of $431 (PITI). I took out a 90% loan at 7.2%. My deposit plus settlement costs came to $7,549.
I remarketed the property 16 days later for $74,900 with monthly payments of $756. I collected a deposit of $3656. This gave me a contract profit of $16,387 and a monthly profit $324; 30 years at $324 a month equals $116,740 of passive (positive) Cash Flow.
Let’s take a look at the first year cash-on-cash return on this property. We do this by dividing our initial investment capital into the first year’s income. The initial investment capital was $7549 divided into $3,656 deposit plus $3,891 received as 12 monthly payments of $324 from the new buyer. This is $7,549 divided by $7,547 = 99% [sic] first year cash-on-cash return.
Investor Property
If you’ve looked at the linked documents, you’ve probably noticed that Burley didn’t really own this house. It was actually owned by one of Burley’s investor partners, John McCants. As Burley’s partner, it’s McCants’ job to put his name on all the paperwork, as well as put up all the front money and make the underlying mortgage payments. He then splits the profits with Burley 50-50. So, McCants supposedly gets, at best, an (admittedly not unimpressive) ROI of 45%, while, in effect, paying Burley an exorbitant 50% glorified property management fee. Of course, McCants also takes 100% of the hit when the buyer isn’t making payments, or when the property is sitting vacant—and that’s going to eat away at your ROI faster than alien blood eats through the bulkheads of the Nostromo.
But, anyway, let’s follow Burley’s example, and pretend John McCants is out of the picture, for now.
Amount of Deposit
As you can plainly see if you look at the Agreement For Sale, the actual deposit was $2,900. Burley is including the first month’s payment with it, effectively making his first “year” include a 13th month. Ironically he can’t even claim that, because his buyers were already in trouble by that time, and paid part of their 13th payment several weeks late. Admittedly, it may seem like quibbling to say the first year cash-on-cash from this deal was “only” 90%, versus 99%, and it might be—if we were talking about someone other than John Burley. Trust me. It’s all downhill from here.
“Contract Profit”
The $16,387—the difference between Burley’s purchase price and his sales price—is made up money. As the term “contract profit” implies, Burley (and McCants) hasn’t actually been paid this money. Instead, what he actually has is a promissory note. If the buyer defaults, any unpaid portion of the balance simply evaporates (and, obviously, so do the profits).
“30 Years”
Burley repeats this one a lot. He loves to give his “students” the impression that, once the buyer signs on the dotted line, no more work will be necessary, other than periodic trips from the mailbox to the bank to deposit the checks. The fact is that most people don’t live in one place longer than a few years—particularly when it’s their first home purchase. Such was the case with this very property. Burley’s buyers, who, as I’ve said, almost lost the house to foreclosure in August of 1999, sold it in October 2005.
Technically, if the house gets sold early, your ROI ends up actually being higher, for reasons I’ll go over in a moment. On the other hand, once the house is sold, you get no more checks. What happens then? Obviously you have to keep finding and buying and remarketing houses. You might be “your own boss” in such a situation, but I’d hardly call it “financial freedom.”
“$324/month for 360 months = $116,740”
Now, there’s no denying that 324 multiplied by 360 is equal to 116,740. However, things get a little more complicated when you start adding words like “dollar” and “month” to the mix.
I find this distortion particularly interesting. It may not constitute incontrovertible proof, but it is certainly very persuasive evidence that one of the following statements is true:
- John Burley doesn’t understand the time-value of money.
- John Burley thinks his students don’t understand the time-value of money, and he isn’t interested in teaching it to them.
Imagine Burley coming to you and offering to give you $324/mo. for 30 years (let’s call it a “promissory note”) if, in exchange, you pay him $116,740 today. Reading his quote above gives me the impression that he would see this as an equitable trade. Hopefully, though, you would recognize it as an appallingly bad deal for you. The question is: How much should you pay someone today in return for 360 monthly payments of $324?
To answer that question you need to know what your other options are (your “opportunity cost”). Where else can you put your money? What if you could choose between Burley’s promissory note and, say, a hypothetical security instrument that pays 6% per year? In that case, you might tell Mr. Burley that you’d be happy to pay him $54,310.68, and not a penny more. Burley, who has just spent $7,549 and taken out a loan for an additional $52,661, politely (and understandably) declines your offer. If Burley seriously wants someone to take his monthly payments, he must continue looking until he finds someone whose next best investment opportunity would pay a maximum of 5.058% interest per year (In actuality it’s worse than that because with Burley’s note there’s a significant risk of default. Note buyers would thus calculate in some discount rate to compensate).
Please note that none of the above illustration is meant to conflate the ROI of the note purchaser with Burley’s cash-on-cash return on his wrap. The ability to use leverage (i.e., OPM) is one of the more attractive aspects of real estate investment. The point I’m making is that Burley is, at best, painting an overly rosy picture (come to think of it, that seems to always be the point I’m making with respect to John Burley!).
Pertinent Costs not included in “Initial Investment”
In keeping with the “overly rosy” theme, Burley fails to include a number of material expenses in his “initial investment” figure. Why doesn’t he mention his staff costs (pro-rated, of course)? Why doesn’t he include his office overhead (again, pro-rated)? Why not the property’s advertising costs? What about its acquisition costs? The house didn’t just fall in Burley’s lap! What about the carrying costs incurred during the 16 days the house sat vacant? Burley includes none of these things in his $7549, yet all of them are real. All of them are significant. This is where I really start to wonder how dumb John Burley thinks his “students” are. Bring any of this stuff up, and you’re bound to hear “Psychobabble! Details don’t matter!” shouted at you, in response.
What about Burley’s time?
Making an accurate estimate of all of the costs I mention above is really an exercise in futility. Your guess is as good as mine. In contrast, determining the lower limit of the value of Burley’s time is a simple matter. We know that if Burley wasn’t being his Level Five Investor self, he’d be in California making upwards of $140,000 per year as a financial planner. We know Burley decided to walk away from this $67.31 per hour, which means he values his time even more than that, but lets stick with $67.31 since we’re sure his time is worth at least that. I think this $67.31/hour is a good proxy for Burley’s expenses, too. After all, you don’t hire staff and occupy an office to make yourself less efficient. All we’re left with, then, is guessing at how much time Burley and his organization spent to make this deal come together.
Was it a week? Then Burley’s ROI on 3320 W San Miguel drops to 66%. Two weeks? Now we’re down to 53%.
You might be looking at those numbers and thinking, “Those are still pretty respectable!” I guess then it’s time to remember that Burley is splitting the profits with an investor. It’s probably also time to remember that Burley’s buyers are necessarily people with bad money-management skills (if they weren’t, they could get a normal home loan like everybody else). Given the tendency of people with poor credit histories to not pay back the money they owe, I would hope that you’d look at the promise of a 26% ROI and see it as a barely acceptable risk premium. Not all properties are bundles of joy, like the San Miguel house. Some, like 2542 W Missouri Avenue, are the demon seed.
Another “Not Special Deal”: 2542 West Missouri Avenue
Purchased in a partnership with his investor Todd Severson on January 13th, 1992, for about $39,000 (based on the loan amount and guessing they put down 10 percent), this house was quickly remarketed to one Gwendolyn R. on the 22nd.
Ms. R’s down payment was almost certainly $1,900, and her monthly payment was $505. If you figure the underlying loan’s interest rate at about 8%, that means that Burley and his partner’s principle and interest payments were around $255/month. Add another $60/month for taxes and insurance, and Burley and his investor were each making roughly $95/month.
Using Burley math, what ROI does that translate to? Initial investment ($4040) divided by deposit plus first year net income ($4300) = 93%.
Everything seemed rosy for over a year and a half. But then, in August of 1993, Gwen missed a payment. In September she missed another one. Then another in October. In a fashion indicative of some measure of uncertainty (read “panic”), and uncharacteristic of his future behavior in this area, Burley sent Gwen two Notices of Forfeiture, the second one a copy of the first, except with additional scribblings to include mention of the missing October payment.
Kicking Gwen out, though, would prove more difficult than just mailing a couple letters. In November she sued Burley and pals, in an attempt to enjoin the forfeiture of her interest in the house. Of course, she was in arrears, and clearly in the wrong (legally, if nothing else), so her suit would only postpone the inevitable. But postponement sounds the death knell for investment returns. In this case it meant zero income from 2542 W Missouri from August 1993 until May 1994, when they were finally free of the lis pendens and found a new buyer. By all indications, this second buyer was trouble-free, living in the house for 5 years, then paying off the loan and, presumably, moving on to a new home.
Now, I ask you, why is it that Burley—a man who is purportedly interested in educating investors—doesn’t include the very educational horror story of 2542 W Missouri as one of the examples in his book? Could it be because Burley isn’t really interested in providing an education?
I leave it for you to decide.
Thursday, June 15, 2006
John Burley's 7 Levels of Investor
George S. Clason, author of The Richest Man in Babylon, had a couple very basic financial lessons to convey:
- A part [10%+] of all you earn is yours to keep
- Pay yourself first
Robert Kiyosaki’s take on it—his “hook,” if you will—comes in the form of his “Cashflow Quadrant.” While this has certainly proved a lucrative idea for him—one that undeniably resonates with his readers—does it really add anything substantial to Clason’s dictums? Has the Cashflow Quadrant ever been a demonstrable part of making anyone—aside from Kiyosaki, that is—financially better off? I really wonder if it’s going to still be around in 80 years.
Burton G. Malkiel, Princeton economist and author of A Random Walk Down Wall Street, expands Clason’s advice to ten rules. Among them are Start saving now; Diversity reduces adversity; Pay yourself, not the piper; and Bow to the wisdom of the market. What Professor Malkiel gains for his readers in clarity, realism, and specificity, he unfortunately seems to lose in allure. Excepting the whole “random walk” notion (which is certainly his “hook”), Malkiel’s avoidance of aphorism and platitude, as well as his presumed distaste for painting pictures of imminent riches in the minds of his readers, is probably the better part of an explanation for his relative obscurity—at least when compared with Clason, Kiyosaki, and John Burley, I mean.
I bring up John Burley, of course, because it’s Burley’s own contribution to the field, the “Seven Levels of Investor,” that I’d like to focus on here. My intent is to argue that, while Burley certainly wants you to believe that his particular exercise in abstraction really presents a unique and illuminating perspective on wealth creation, it really just boils down to obscurantism.
What are the 7 levels, anyway? Burley provides his definitions in a free report downloadable from his web page, here. In summary:
Level 0 – The Non-existent
Level 1 – The Borrower
Level 2 – The Saver
Level 3 – The Passive Investor
Level 4 – The Automatic Investor
Level 5 – The Active Investor
Level 6 – The Capitalist Investor
Note immediately that, in a way analogous to Kiyosaki’s abuse of the terms “asset” and “liability,” Burley has taken the word “investor” and pummeled it beyond recognition. The first three levels aren’t “investors” at all! Neither are levels 5 or 6, as I’ll be arguing in a moment—at least not in any sense relevant to Burley’s concept of “financial freedom.” Furthermore, Burley’s overly broad definition nonetheless fails to include one of the more important types of “investor”: the college student. This omission is characteristic of the get-rich-quick “gurus,” who all pooh-pooh education, and seem to have no concept whatever of basic economic concepts such as the time-value of money, comparative advantage, and opportunity cost (or, if they do, they keep this knowledge to themselves).
But what about Levels 3 and 4? Well, at least you can say that they actually fit the colloquial meaning of the term “investor.” I’ll also admit that, while I disagree with a number of things, on net I think Burley has some good advice for Level 4 Investors. But his good advice makes my point: He doesn’t manage to say anything that Clason and Malkiel didn’t already cover—and cover better.
In his discussion of Level 3, Burley obviously intends to inoculate his dupes against the inevitable criticisms that will be made by people like me. Standing the skeptics up as straw men and calling us the “It Can’t Be Done” Passive Investors, Burley makes a big show of knocking us down:
The “It Can’t Be Done” Passive Investor has determined that all investments involving more than the most basic research by the investor, that promise much more than bank interest rates of return are beyond them. They believe that higher rates of return “can’t be done” by other than the most “gifted,” “lucky” or “connected” business people, “corporate highfliers” or “shady wheeler dealers.” They truly believe that high rates of return on investments are either impossible, probably illegal or available only to the chosen few. They believe that the knowledge and skills required to even recognize such investments are beyond THEM, in their present circumstances.Bla bla bla bla bla! Seriously, who believes that high rates of return are illegal or impossible, except maybe Fidel Castro? Burley continues with the baseless insults and vacuous “arguments” for quite a while after that. What he says amounts to a gross distortion and oversimplification of the efficient markets hypothesis (EMH). The EMH, a concept I have previously gone over, is not just something spouted by broke, envious “cowards” who are intent on sabotaging your future. It happens to be backed by mountains of empirical evidence collected over decades. Don’t take my word for it. Read Burton Malkiel’s book on it, for example. Or, surprisingly, you can just take Burley’s word! Burley reveals his own implicit belief in the EMH on page 15 of his report. Counseling the Level 4 Investor, Burley, in a fit of rare clarity, says:
Stick to owning solid stocks and proven growth Mutual Funds. Do not attempt to outsmart the market. Use a fund like the US Vanguard Index 500 fund that closely ‘mirrors’ the S & P 500 Index. This index outperforms two-thirds of all Mutual Funds, year in and year out. Over 10 years this will historically provide you a return that will exceed 90%+ of the “professional” Mutual Fund managers. [My emphasis]An ironic little twist in all this: Guess who serves on the board of directors for the Vanguard Funds... Burton G. Malkiel!
So much for Levels 3 and 4!
As far as Levels 5 and 6 are concerned, I believe Burley consciously avoided using a term that would have fit them much more nicely: the entrepreneur. Burley is clearly not stupid. He’s gotta know that the use of this word will strike fear in the hearts of those on the quest for easy money, because following on the heels of “entrepreneur,” invariably, is a four-letter word that the Kiyosakis and the Burleys of the world despise: Risk.
It is particularly important to understand this: risk is not simply inextricably intertwined with the entrepreneur; the assumption of risk is the role of the entrepreneur in the free market economy. Risk is the entrepreneur’s function! You’ll, of course, never hear this from Kiyosaki or Burley. They want you to believe exactly the opposite: that it’s really your job that’s the risky thing, and the entrepreneur, the one who hired you and has agreed to pay you for your time—pay you whether the company is in the red or in the black this year—is really the “secure” one. This is pure, unmitigated, utter bullshit!
I’ll take a look at some of the particulars of Burley’s Level 5, but before I do, let me just touch on Level 6 briefly, to get it out of the way. Level 6 is the rarified air of the true innovators of the world—the Gates’s, the Winfrey’s, the Stewart’s, the Trump’s… Innovators are those who, throughout history, have been responsible for most of the improvements to the human condition (Hmmm, well… with the possible exception of Bill Gates, maybe the names I listed above don’t quite fit into that category…). Burley mentions Level 6 pretty much as an afterthought, I think because he recognizes that it’s unrealistic to consciously strive for this level. Stellar entrepreneurial success is not called “making a fortune” for no reason.
So, back to Level 5. This is Burley’s “sweet spot.” Burley and his acolytes love to concoct all sorts of mythology about the Level 5 Investor. Level Fives have “principles and rules” for investing… They’re “visionaries who use lateral thinking to develop ideas and methods no one else has thought of”… They brag “about how many vacations and three-day weekends they’re able to take”… They “don’t want to wait until they’re 60 to be financially secure”…and on and on and on. Who wouldn’t want to be Level 5? Where’s my credit card so I can pay Burley to tell me all the secrets of the Level 5 Investor?
As I said before, the Level 5 Investor isn’t an investor in the sense that Burley wants you to take it—i.e., a person who sticks his money someplace and then waits for the big checks to roll in. Burley is careful to pick a positive yet very generic label for this level. To call the “Active Investor” what it really is—the sole proprietor, the franchisee, the small-business owner—doesn’t fit well with the image Burley needs to convey in order to keep his dupes interested. He can’t afford to give his “students” the impression that being at Level 5 takes real work. 14-hour days 7 days a week for a couple years or more—the reality of the typical start-up, run by someone interested in making it successful—doesn’t quite jibe with the notion of “financial freedom” envisioned by Burley’s target market. These are the sort of people, you realize, who respond positively when Kiyosaki remarks, “I’m lazy. I’m also incompetent. The trouble with being competent: People call you up [to ask you to do things for them]… I keep myself incompetent...” So, Burley, quite rationally, dances around this issue. He keeps the description of the Active Investor in his report fairly brief. Among other things,
[Level Fives] consistently strive to optimize performance while minimizing risk. It is normal for this type of investor to have long-term annual rates of return of 20%-100%+. They intimately understand money and how it works. Level Five Active Investors become very wealthy. Their main working focus is on increasing their assets and thus their cash flow.What’s annoying about the above characteristics is that, aside from being arbitrary, they’re entirely descriptive in nature—meaning that you won’t know you’re a Level 5 Investor until it’s too late for you to give a crap about it. Didn’t become wealthy? Well, you obviously weren’t really a Level 5. Didn’t earn 20%+ on your money? Sorry, you just didn’t have what it takes to be Level 5. Did you get filthy rich without any appreciable understanding of the “money game”? Clearly you're a Level 3 PIG who got lucky. Anyway, you get the idea…
In the final analysis, though, Burley’s descriptions of the 7 Levels of Investor aren’t meant to instruct or illuminate. Instead, Burley intends to inspire in his readers a burning desire to learn the Secrets of Professional Investors so that they can Win the Money Game, obtain the Blueprint for Success and The Keys to the Vault. Attend the Boot Camp and your status as a Level 5 Investor will undoubtedly be assured! Awareness, Attitude, and Action—i.e., pulling out that credit card and lining Burley’s pockets.
“But einzige,” I can hear you interjecting, “your argument seems to imply that becoming rich is an impossibility. The fact that rich people actually exist is a clear refutation of this notion. Ha!”
Here’s something that seems lost on all get-rich-quick scammers out there—let’s call it my “hook”, my aphorism:
Einzige’s Get-Rich-Quick SecretYou never seem to hear this from the likes of Burley and Kiyosaki. The idea that an entrepreneur is beholden to the whims and tastes of the consuming public is an afterthought—if it is even mentioned at all. This idea, however, is central to the creation of wealth. Zalmon Gilbert Simmons did it with mattresses… Daniel Gray Reid did it with tin plates… Jeremiah Milbank did it with condensed milk… Henry O. Havemeyer did it with sugar… Rockefeller did it with kerosene… Ray Kroc did it with hamburgers… Andrew Carnegie did it with steel… John Sperling did it with an online private University… The list is endless! It has always irked me that the real estate gurus push the bullshit myth that all the wealthy got that way via real estate.
Do something that others value
If you can put my Secret to work in combination with what I’ll call “Einzige’s Corollary” –
Do your thing better and/or cheaper than the next guy
– then you’ll really be off and running. If you can corner the market, even better! This is a little more difficult, though, because keeping competitors and imitators from biting at your heels is almost always impossible. There are still examples out there, though. Howard Stern is wealthy because his “product” is Howard Stern—though he has competition in the broader market for “shock jocks.” Michael Jordan is a similar case. He’s the only one capable of selling Michael Jordan, but there are others out there selling the product called “talented athlete.”
I can hear you now saying, “But einzige, your ‘secret’ isn’t helpful at all! Being an innovator isn’t easy!”
Ahhhh! Now you’re getting it. On the other hand, maybe it’s time to defer to the greater wisdom of überBurleyist Robyn Grinter on this one: “If you think you can, you’re right. If you think you can’t, you’re still right.”
Now, maybe there’s an improvement on Clason!
Wednesday, May 31, 2006
The Burleyists - Robert Yang
If you're at all interested in what John Burley has to say on financial freedom or real estate investment, then you'll very quickly find your way to the John Burley Discussion Forums. I have spent a good deal of time reading the messages there, myself - originally because I was in thrall to the beliefs, but more recently as research for my Burley-related posts here (and I admit there's an element of sick fascination involved, as well).
One of the dangers of reading the forums for extended periods, however, is that you might find yourself starting to almost believe the hype. Message after message from "successful students" who claim to be living the dream and making fistfuls of cash (aka, "Progressive Profits") as a result of following Burley's advice is enough to weaken even my skepti-sense after a while. It takes a conscious effort to remember that
- Correlation does not necessarily mean causation (e.g., just because night follows day does not mean that day is the cause of night)
- Anecdotes are the weakest form of evidence for something (precisely because of reason 1, but also because they aren't necessarily representative of the target population as a whole)
- Most importantly: this is Burley's promotional site! You can find rah-rah sites on the web for just about any absurd scam you can think of - from homeopathic "medicine" to "over unity" technologies.
Let's have Robert introduce himself:
Hello, my name is Robert Yang.
I am the Host of yisemen.com, a site devoted to your financial education. I just turned 35 and currently in semi-retirement after achieving financial freedom for myself and my family. It did not start out this way. In October 2002, after realizing I lost $500,000 in the stock market with a high probability of been laid off from a Fortune 500 company that I worked for since college. I dedicated myself to the “1,000 days challenge” to be out of the rat race (achieve financial freedom). I was fortunate to have many mentors and found many supportive networks along the way. I have indeed achieved financial freedom in less than 3 years.
However, it was not an easy road traveled. Being a W2 wage earner with a full-time job and a family to take care of, it was hard to get started. I learned enough lessons along the way that I am now in a position to share my experiences with you and support you if you too have the burning desire to one day quit your job to spend more time with your family and having the free time to do what you like to do, not what you have to do. I honor you for taking your first giant step forward and joining me and my friends in the journey toward financial freedom! As one of my mentor Anthony Robbins likes to say, “Life will never be the same again!”
How did I came up with the name yisemen”? Last year, when I was interviewing CPAs for one of my companies, I was asked to give the names of our principles. I was providing the names one by one, she noticed that my partner, Jeffrey, my advisor, Edwin, and myself all shared the last name starting with the letter Y. So, she jokingly said, “you guys are the three Y’s men (wise men). I like the name a lot and decided to keep this nickname and be one of the – “yisemen”.
Keep the passion alive,
Robert Yang
Unfortunately some time in the past 3 months Robert's web site for Yisemen Financial has all but disappeared. All that remains today is Google's cache of the site.
One has to wonder what happened. Yisemen Financial had so much going for it! With the incomparable teachings of Robert Kiyosaki, Matthew Chan, and John Burley behind it, as well as the indispensable "burning desire" of Robert Yang - Burleyist extraordinaire - to succeed, it just doesn't seem possible that the company could have met with failure. Of course, the other possibility is that Robert has taken that fabled quantum leap out of the rat race and has no need of Yisemen Financial any more.
But wait! Robert says that he had already done that before starting his site, so that can't be the answer - and clearly the financial education needs to continue because, for example, I have yet to leave the rat race. So none of it makes any sense!
Whatever happened, though, I hope Robert Yang is "keepin' the passion alive" out there somewhere!
Google's cache of www.yisemen.com is undoubtedly going to be cleared soon, and I can't bear the thought that Robert Yang's invaluable insight might be lost. So, for the sake of posterity, here are a couple choice quotes (I really want to do more, but I'm a little worried about already being on the edge of fair use)...There are no bad investments
There are bad investors
This is so true. It is the investor, who finds a way to create value, and make it a good investment. I lost tons of money in the stock market because I was a bad investor prior to October 2002. I thought I was a great investor when I saw one of my high-tech stock portfolios grow from $20,000 to $240,000 between 1993 to 2000. Now looking back, I realized I was just a Level Three pig who got lucky with the tech run in the 90s. I had no limit order in place to sell my stocks when it fell below a certain price. I was greedy. I took everyone’s advice – invest for the long term. I didn’t cared how high the PE (Price to Earnings) ratio was – thinking there are more fools behind me who will pay even higher prices for my stocks. I did not realize that stock is not a secured investment, where the down side can be 100%. I had absolutely no control over my investment in the stock market.
Yet, not all investors lost money during the stock market crash of 2001. Warren Buffet did just fine for his investors. Many seasoned investors had hedge position. Some even welcome the big swing in the market as they utilize options to earn very high return on their money. So, the lesson is – It is not the investment, it is the investor that creates the return.
...
So, what is the secret for getting out of the rat race?
My experience tell me that first you have to address the basics. Once you have a good fundemental, you can speed the procoess up by going through self-improvement seminar, having mentor, network with other successful people.
1) You must save a part of you earn... It a sample mathemtics. When you get your check every month, put at least 10% to 20% aside for investing before you pay for everything else...
2) Know your financial freedom gap
Financial Freedom Gap = Expense - Passive Income
Track your expense for few months and know how much money you needed per month to live. Start invest for passive income. Most people only invest for capital gain (which help to increase your networth, but does nothing to get you the income you needed to be out of the rat race).
3) How much money do I need to retire?
It depends on what rate of return you can get.. Example if you need $5,000 per month to cover your expense, then,
APR Capital Needed
2% $3,000,000
8% $750,000
15% $400,000
4) Turn your liability (which creates expense) and un-productive assets (which generates no passive income) into true assets (that produces income for you every months).
5) Network with other sucessful investor and co-invest with them when you starting out.
6) Improve your skills by going to seminars, listen to audio CD, get a mentor if you want to speed up the process.
7) Play Cashflow 101 at least once a month for the next 12 months
Those are some of the fundmentals...
Keep the Passion Alive,
RobertY (Host)
Feeling financially freer, yet?
Saturday, May 13, 2006
John Burley's Advice vs. Astrology
Real estate investment “guru” and self-described “prosperity trainer” John R Burley (about whom I have written extensively here), arguably most famous for his Progressive Profits infomercial, used to offer an “intensely powerful” quarterly newsletter, called The Burley Chronicles. I believe a subscription cost around $99 a year. It’s apparently discontinued—I suspect for reasons that, in a moment, I’ll be making abundantly clear—but if you enter your mailing information at his web site then you’ll probably be sent your own complimentary issue, along with a bunch of other promotional materials.
In my copy, the 3rd issue from 2001, Burley welcomes readers with, “The learning, fun, and education continues.” Much of what follows is an “education” that isn’t worth 10 cents—let alone $99 a year! For example, in the same article, Burley says:
The cause of the depth of the current US slowdown (read ‘recession’), may be debated, but there is now general consensus regarding the timing and likelihood of economic recovery. Everybody agrees that they have absolutely no idea!I read this stuff and become physically ill. This is “investment advice” on a par with what you’d get out of your daily horoscope! To prove my point, below I have taken several of Burley’s nuggets of wisdom (or something) and randomly interspersed them with items I’ve pulled from daily horoscopes. I challenge you to tell them apart.
Everyone is searching for better profits and economic news. Are they looking in the right places? As a Level Five investor, where do we look for increased returns on our investments?
As I often say, it is not really important where you look for your investments. It is more important how you look! [emphasis original]
Looking at investing with the lateral thinking mind of the Level Five investor is the key to recognizing the limitless opportunities that exist in any market—and particularly in a recession market—for double digit and higher returns.
AI’ll reveal the answer in the comments at some point in the future. In the mean time, feel free to offer up your own guesses.
Learn to produce results without agreement from others. It’s a marvelous skill to have, and will be quite profitable. And once you get past the nervousness, you’ll be very strong.
B
Remember, all coins have two sides and both sides are shiny if polished properly and viewed from the proper perspectives! Awareness, Attitude and Action!
C
We are still playing our own game by our own rules and the playing field grows larger by the day.
D
Don't worry if what you try doesn't work. It's just as important to know what won't. It narrows down the seemingly endless possibilities.
E
There are so many opportunities around these days that you might actually have to flip a coin to help you decide which one to pursue first.
F
Invest in an area that you have long been curious about. Get some of those old questions answered and you'll sleep better at night.
G
Remind people to look at the facts if they're getting emotional.
H
The sentiment of abundance that has driven growth over the last decade has taken on the scent of scarcity. This is when the astute and prepared rise above the naysaying rabble.
I
The workload is intense and the objective is muddled. Before you knock yourself out, find out what needs to be done and what doesn't. Your efforts will be appreciated.
Thursday, May 04, 2006
John Burley's Dog and Pony Show
In my post talking about John Burley’s book, I hypothesized that it’s probably as information-rich as his Boot Camp, even though it's $4980 cheaper. If you’ve read Burley’s promotional material for his Camp, you might object to my characterization, because, for example, on Day 2, the attendees are taken to downtown Phoenix to witness a trustee sale. Such an activity, however, is a complete waste of time, for several reasons.
In the first place, what is there to learn by attending a trustee’s sale? It’s just your standard auction, and who isn’t familiar with that? This is the 21st century. Who hasn’t been on eBay?
Next, as even Burley points out, these auctions are all cash. The typical Burley student doesn’t have any cash—or why would they be attending the Boot Camp? On top of that, most of the attendees are there to learn about Burley’s wrap technique, the point of which is to use as little cash as possible (otherwise your cash-on-cash returns evaporate). So, not only are Burley’s students unlikely to ever be capable of bidding in a trustee auction, they’re not likely ever to want to do so, either.
Something tells me that Burley also probably doesn’t mention a number of serious drawbacks to the trustee sale. It’s rare for a “distressed property” to even get to the auction, so the ones that do are likely to have a storied history. The owner has to have played ostrich—putting the mortgage several months into arrears (necessary before the foreclosure process can even begin). Then public notice of the auction has to happen at least 60 days prior. A lot can happen in those 5 to 6+ months. How many investors specializing in distressed properties do you think have spoken to the owner during that time (and still didn’t manage to put together a deal)? How much maintenance do you think the owner has been doing on the property? Do you think the owner is going to be happy to leave? If the house gets to auction then there’s a near certainty that it has a real problem—one that’s probably not going to be profitable for you to solve, even at “thirty to seventy cents on the dollar.”
Once bidding on the house starts, what do you think happens? The first thing is that the bank holding the primary mortgage bids the amount of the balance owed—to ensure they get paid. If that’s 90% of the market value of the home, then where’s your money going to be made? And what if it’s you who ends up making the winning bid? The question that should immediately come to mind is, “What do all these other people know that I don’t?” The Winner’s Curse isn’t just some witch doctor’s superstition.
Given all this, Boot Camp attendees are, in reality, paying about $500 for little more than a dog and pony show. John Burley, on the other hand, is laughing all the way to the bank.
Wednesday, May 03, 2006
The Burleyists – Robyn Grinter
I am confident that not a day goes by during which John Burley doesn’t fall to his knees, clasp his hands together, look reverently toward the sky, and thank his Lord and Savior for Robyn Grinter.
Robyn, you see, is proof positive that anyone can do it, as long as you have faith and believe in yourself! Robyn is the hero and the inspiration for all the ChavaRicas out there, who think, “If she can do it, then I can, too! What do all you psychobabbling naysayers know? Success leaves clues! Plus, Robyn obviously cares about my success, so I believe her!”
Robyn says:
You see 95% on success in investing is in your head it is as simple as “if you think you can’t you are right” or “if you think you can you are right” either way you are right so just think the right thoughts. [sic]Robyn knows of what she speaks, since she’s done 220 real estate deals since 2001. So, clearly, if you fail as a property investor it’s 95% certain that your failure was simply the result of the weakness of your convictions.
Burley couldn’t have asked for a better Burleyist.
Saturday, April 29, 2006
7 Steps to Financial Freedom
Back in 2000 John Burley published a book, called (Australia’s) Money Secrets of the Rich! - Learn the 7 Steps to Financial Freedom. A couple months ago I saw a copy go up for auction on eBay, and decided I’d buy it, even though the shipping cost from Australia would be a bit steep (It turned out that I was the only bidder, and the shipping cost was twice the price of the book!). Oh, the things I do in the service of keeping you informed! In the book’s introduction, Burley makes reference to a US version that was supposedly completed before the Australian edition. When I read that I thought, “Crap! All that shipping cost wasted!” Strangely, though, such a version apparently doesn’t actually exist—at least in published form—yet. Whew!
Before I go into detail about many of the things I don’t like about this book, let me begin by going over what I do like about it: It’s not an awful book. You could do a lot worse than following the advice it contains (most of it, anyway). That having been said, it is plagued with the same problems that permeate all the rest of Burley’s products. Much of the good advice that Burley gives has been said better elsewhere. It over-promises and under-delivers. It’s 450ish pages long, but its core messages can be had—for free, mind you—much more compactly, in various places around the web. If you've been paying attention, you'll no doubt notice that the "7 Steps" in the book are basically a rehashing of the "7 habits" that I've mentioned before. Why not simply read those links and save yourself the $20?
Speaking of that, it seems highly likely that the guy at DPD Marketing is telling the truth when he says that this $20 book contains more useful information than you’ll get at Burley’s $5000 Phoenix boot camp. I base this theory on my prior experience with some of Burley’s other products. This is particularly ironic, given what Burley has to say in chapter 10, Money Step #6: Financial Competence, in a section called “25 Financial Competence Purchasing Techniques.” In item 3, on page 100, Burley writes:
Be aware of the persuasion techniques (‘weapons of influence’) used to get you to spend more. Typical techniques are: exploiting the stereotype of ‘expensive = good’ by inflating prices to make an item seem desirable and/or then discounting it to make it seem a bargain for its quality; the ‘contrast principle’ whereby an expensive or overpriced item is presented and/or sold first in order to lessen the perceived cost and increase the saleability of subsequent cheaper presented items, or options; or the scarcity technique whereby items are marked ‘For 5 days only’ or ‘A limited time only’ or ‘Limited edition’, etc. These are just a few of the many influence techniques described by Robert Cialdini in his groundbreaking book Influence, The Psychology of Persuasion. Be aware of these techniques. [emphasis original]A few pages further on, Burley expands on the “expensive = good” concept, writing:
In western nations we are conditioned that we need to pay more to get more. That precept may seem logical. In fact it is, for the companies selling you products! It is an assumption that sits at the very foundation of advertising. [emphasis original]In Item 10 of Burley’s 25 purchasing techniques Burley writes that it is “lunacy” to ever pay retail. I certainly can’t argue—but here’s the irony to all this: In effect, Burley is counseling his readers to never buy any of the crap he’s selling on his web page, since he himself uses all of the advertising techniques he’s warning you against. This is one bit of Burley advice that I can get fully behind!
The book’s peculiarities start well before chapter 10, however. In its introduction, Burley gets briefly autobiographical:
I was 29 years old, newly married...but despite my well-above-average income, I was broke, in debt and going nowhere fast.Some of the oddities in those paragraphs might simply be chalked up to poor editing. For example, the claim that he was broke at 29, studied money “solidly” for 10 years, and yet could have retired at 32 makes little sense. Maybe it’s a typo, and it should say “1 year,” instead. For what do we know about John Burley?
…
I realized that just making more money was not the answer. I had to learn how to properly manage my money.
…
For the next 10 solid years I made it my mission to locate and study all the information I could find on the subject of money: making it, keeping it, spending it and investing it... I developed, experimented and took action...
…
By age 32 I was in a financial position to be able to retire! I was in a position to be able to live off the positive cash flow from my investments, and if I so desired, never have to work again! [emphasis original]
Burley was 29 in 1990. He was a financial planner (a glorified insurance salesman) making $140K/year, living in Felton, CA. That year he purchased 5 VA foreclosure properties (likely for zero down + VA transaction fees, though about that I’m not entirely sure), quit his, um, financial planning practice, then moved to Phoenix and into a $220,640 home (bought very creatively for zero down using a combination of seller financing and future balloon payments). These are sure ballsy moves for someone who supposedly was broke, deeply in debt, wanted to “properly manage his money,” and didn’t know what he was doing! Needless to say, I am a little incredulous.
I’ll explore this a little more, as well as delve into other sections of the book, in upcoming posts.
Thursday, April 06, 2006
John Burley's Foreclosures
My friend Jim read my previous Burley post and asked me if I could provide more detail about how often John Burley’s buyers default on their loans and have to be evicted. I figured it would be a good idea to address the issue here on Die Eigenheit, rather than only in a private response to Jim.
Below is a list of links to the public records available at the Maricopa County Recorder’s office. More specifically, the links bring up lists of the Affidavits and Declarations of Forfeiture associated with John R Burley, his legal entities, and his investor partners (the one’s I know of so far, anyway). Some overlap is inevitable, as many documents have both Burley’s name and the name of his partners on them, but you can see that the lower limit is 32 foreclosures. Follow some of the links and you’ll discover that there are, in truth, many more than that.
Burley, in his guest lecture (for lack of a better word) on Kiyosaki's Financial Literacy tape set, says, rather unequivocally, that he likes it when his buyers default. Since Phoenix AZ saw explosive real estate price increases from 1990 to around 2005, that attitude is not hard to understand (leaving aside the ethical issues - as Burley has done). Once Burley gets the house back he can turn around and sell it to someone else for a higher price and larger monthly spread - now there's some Progressive Profits for ya!
Burley And Associates – also here
John Burley – also here
Adrian barrow – also here
Bill Burley aka William burley – also here
Bill Tyma
Charles Norris
Christian Cluff
Donald Burley
Donald Quinn
Frank Batmale
Old Southwest LP
Gloria Iorio
Bubbas treasure chest LP
James Mullaney
Mark Hoose
Michael Rossum
Monte Bosch – also here
Robert Aikman
Sukan Makmuri
Thomas Bartlett
Todd Severson
Southwestern Endowment Fund
Corumn
Maxwell – also here
Old Southwestern LP
Wednesday, April 05, 2006
The Coin's Flip Side
Since Burley's homebuyer's web page is ez2own1.com, I'm kicking myself for not thinking earlier that he'd also want to have ez2sell1.com for distressed home sellers, but there it is!
Now all we need is ez2invest1.com...
Oh, check out this quote from the link above:
This dynamic man has helped thousands of families avoid foreclosure and financial ruin through his home purchasing program.Gotta love it! If that's not incontrovertible evidence that John Burley is after a cult of personality then I don't know what is.
Let's take his dubious "thousands" claim at face value, for the moment. He, of course, fails to mention this corollary fact: He has "helped" many "thousands" more families into foreclosure and financial ruin by selling overpriced homes at exhorbitant interest rates to people with poor money-management skills, and then kicking them out when they can't pay.
Apologists would argue - amid cries of "Psychobabble!" - that it's not Burley's fault his buyers can't live up to their part of the purchase agreement. That is no doubt true. But if John Burley is genuinely interested in helping people "achieve a rich, full life, filled with prosperity and abundance," then how can he keep a clear conscience when he sells to an unsophisticated neophyte homebuyer with poor credit - someone he knows has a high likelihood of defaulting on the loan? Can he really have it both ways?
Tuesday, April 04, 2006
A Burleyist?
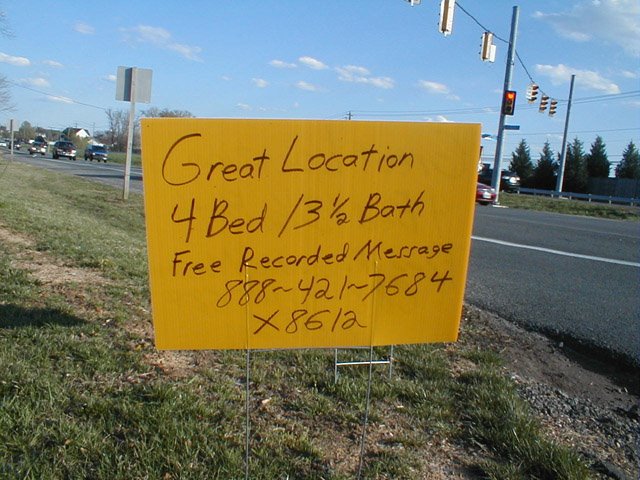 These signs just went up a few days ago. They are all along my route to work, so I'm sure there are many more like them scattered all throughout the Great Falls/Reston area. The top one is on the corner of Utterback Store and Leesburg Pike. The one below is at Bowman Towne and Fountain, and the third one is at New Dominion and Towne Center.
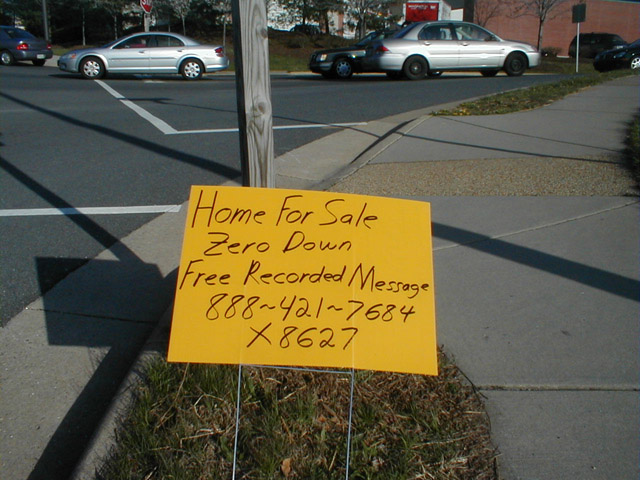 Is the owner of these signs a Burleyist? Well, given that there are a finite number of ways to invest in and market real estate, but a seemingly endless number of "gurus" interested in selling you all their supposed "investing secrets," probably not. On the other hand... the corrugated plastic sign... the phrase "zero down"... doing it on the cheap... the recorded message... no mention of the home's price... all are indeed Burley techniques.
 I haven't listened to the message(s), yet, but I bet it also doesn't mention an asking price - only how much to "get in" and how much per month.
Note that there are two different extensions mentioned. I initially thought that this meant the investor had two places for sale. However, I used one of these recorded message systems while I was a Realtor, and the way it worked was the first two numbers were the mailbox number, while the second two numbers were up to you. They're designed to be an indicator to you about which ads - if any - generate the best response.
I'll be watching the signs closely to gauge how long it takes the place(s) to sell.
Subscribe to:
Posts (Atom)

